Estate planning is one of the most important parts of financial planning, yet it is often delayed.
Many people assume estate planning is only for wealthy families, retirees, or people with large businesses. In reality, most adults can benefit from having a basic plan in place.
Estate planning helps you decide what happens to your property, money, accounts, personal belongings, digital assets, and responsibilities if you become incapacitated or die. It can also help protect your children, reduce confusion for loved ones, and make difficult moments slightly easier for the people you care about.
A basic estate plan may include a will, beneficiary designations, powers of attorney, healthcare documents, and an organized record of your financial information. Some people may also benefit from a trust, depending on their assets, family situation, location, and goals.
Estate planning is not about expecting the worst. It is about preparing responsibly.
https://trendminers.online/retirement-planning-in-your-30s/
This guide explains estate planning basics, the key documents to understand, common mistakes to avoid, and practical steps to start protecting your family’s financial future.
What Is Estate Planning?
Estate planning is the process of organizing your legal, financial, and personal affairs so your wishes can be followed if you become unable to make decisions or after you die.
Your “estate” includes more than a large home or investment portfolio. It may include:
- Bank accounts
- Retirement accounts
- Investment accounts
- Real estate
- Vehicles
- Life insurance policies
- Personal belongings
- Business interests
- Digital assets
- Intellectual property
- Pets
- Debts and liabilities
- Family heirlooms
- Online accounts
- Cryptocurrency or digital wallets
An estate plan helps answer important questions, such as:
- Who should receive your assets?
- Who should care for minor children?
- Who should make financial decisions if you cannot?
- Who should make healthcare decisions if you cannot communicate?
- How should your debts and bills be handled?
- Who should manage your estate after your death?
- How can your family find important documents and accounts?
- What happens to your business, property, or digital assets?
Without an estate plan, many of these decisions may be made according to state laws and court processes rather than your personal preferences.
Estate planning rules vary by country, state, and local jurisdiction. This article provides general educational information, not legal advice.
Why Estate Planning Matters for Everyone
Estate planning is useful for people at many stages of life.
You may need a plan if you are:
- Married
- Single
- A parent
- A homeowner
- A renter with savings and accounts
- A business owner
- Self-employed
- Divorced
- Blended-family parent
- Caring for aging parents
- Supporting a disabled family member
- Living with a partner without marriage
- Building retirement savings
- Owning digital assets
- Responsible for pets
Even a simple estate plan can reduce stress for loved ones.
For example, if you have a child, naming a guardian in a will can help communicate who you want to care for them if both parents die. If you have retirement accounts, updating beneficiaries can help ensure those assets are transferred according to your wishes.
If you become incapacitated without powers of attorney or healthcare documents, family members may need to go through court processes to gain authority to make decisions for you.
Estate planning is about control, clarity, and protection.
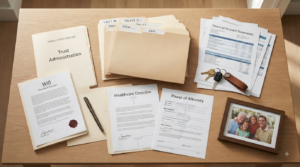
The Core Documents in a Basic Estate Plan
A basic estate plan may look different for every household, but several documents are commonly included.
A Will
A will is a legal document that states how you want certain assets to be distributed after your death.
A will can also allow you to:
- Name an executor to manage your estate
- Name guardians for minor children
- State who should receive personal property
- Explain how remaining assets should be distributed
- Provide instructions for specific gifts
- Express certain wishes for pets or personal items
The executor is the person responsible for handling estate tasks, such as gathering assets, paying valid debts, filing required documents, and distributing property according to the will and applicable law.
A will does not necessarily control every asset you own. Some accounts, such as retirement accounts, life insurance policies, and jointly owned property, may pass according to beneficiary designations or ownership rules.
A will can still be one of the most important documents you create.
A Trust
A trust is a legal arrangement that can hold and manage assets for beneficiaries.
There are many types of trusts. One common type is a revocable living trust, which may allow you to manage assets during your lifetime and provide instructions for how those assets should be handled after death or incapacity.
Trusts may be useful for people who:
- Own property in multiple states
- Have significant assets
- Have minor children
- Have blended-family concerns
- Want more control over how assets are distributed
- Want to plan for a family member with special needs
- Own a business
- Want more privacy than a public probate process may provide
- Want to simplify the transfer of certain assets
A trust is not automatically necessary for every person. It can involve legal costs, ongoing maintenance, and the need to properly transfer assets into the trust.
A trust that is created but never funded may not work as intended. Because trust planning is complex, speak with a qualified estate planning attorney before creating one.
Durable Financial Power of Attorney
A durable financial power of attorney allows you to name someone to make financial decisions on your behalf if you become unable to do so.
The person you choose is often called an agent or attorney-in-fact. They may be authorized to handle tasks such as:
- Paying bills
- Managing bank accounts
- Handling tax matters
- Managing investments
- Selling or maintaining property
- Applying for benefits
- Working with insurance companies
- Managing business decisions
The powers you grant can be broad or limited, depending on the document and local laws.
Choosing an agent requires trust. This person may have significant access to your financial affairs. Select someone responsible, organized, honest, and willing to act in your best interest.
You may also name an alternate agent in case the first person is unavailable.
https://trendminers.online/401k-vs-ira/
Healthcare Power of Attorney
A healthcare power of attorney allows you to appoint someone to make healthcare decisions if you cannot make or communicate them yourself.
The name of this document varies by state. It may be called a healthcare proxy, medical power of attorney, healthcare agent designation, or another similar name.
Your chosen agent may make decisions about medical treatment, care providers, facilities, and other health-related matters according to the authority granted under your document.
This role can be emotionally difficult. Talk with the person you choose about your values, preferences, and wishes.
Living Will or Advance Healthcare Directive
A living will, often included in an advance healthcare directive, is different from a regular will.
It generally explains your preferences for medical care if you are unable to communicate. This may include decisions about life-sustaining treatment, artificial nutrition, resuscitation, pain management, organ donation, and end-of-life care.
The exact terms and legal effect vary by location.
A healthcare directive can reduce uncertainty for family members during a difficult time. It gives your loved ones guidance instead of forcing them to guess what you would have wanted.
Beneficiary Designations
Beneficiary designations are among the most important and most overlooked parts of estate planning.
Many accounts allow you to name beneficiaries directly. These can include:
- Life insurance policies
- 401(k) accounts
- IRAs
- Pension plans
- Annuities
- Bank accounts with transfer-on-death designations
- Investment accounts with transfer-on-death designations
- Health savings accounts
Assets with beneficiary designations may pass directly to the named person, often outside of a will.
This means an outdated beneficiary form can create major problems.
For example, if your will leaves an IRA to your children but your old beneficiary designation still lists a former spouse, the account may pass according to the beneficiary designation rather than your will.
Review beneficiary information after major life events, including:
- Marriage
- Divorce
- Birth or adoption of a child
- Death of a beneficiary
- Changes in relationships
- Job changes
- Opening new retirement accounts
- Changes in your financial goals
For retirement account guidance, read 401(k) vs IRA: Which Retirement Account Is Better?.
Guardianship for Minor Children
If you have minor children, naming a guardian may be one of the most important reasons to create a will.
A guardian is the person you would want to care for your children if you die or become unable to care for them.
You should discuss this responsibility with the person before naming them. Consider:
- Their values and parenting style
- Their relationship with your children
- Their health and age
- Their financial stability
- Their location
- Whether they are willing to serve
- Whether they have children of their own
- Whether they have the space and resources to care for your children
You may also name an alternate guardian.
The court may ultimately make the final decision based on the child’s best interests, but naming your preference can provide important guidance.
Digital Estate Planning
Digital assets have become an important part of estate planning.
Your digital life may include:
- Email accounts
- Cloud storage
- Social media profiles
- Online banking
- Investment platforms
- Digital photo libraries
- Subscription services
- Cryptocurrency wallets
- Websites and domain names
- Online businesses
- Digital products
- Password managers
- Loyalty programs
- Online payment accounts
Without clear instructions, loved ones may struggle to locate accounts, access files, close subscriptions, protect against fraud, or manage business assets.
Create a secure inventory of important accounts and digital assets. Do not put passwords directly into your will because a will may become public during probate. Instead, consider using a reputable password manager, secure encrypted file, or other protected system.
Leave clear instructions about where your trusted representative can access this information.
If you own a website, digital products, or an online business, include information about domain renewal, hosting, payment accounts, intellectual property, customer data, and business operations.
How Probate Works
Probate is the legal process used to administer a deceased person’s estate.
During probate, a court may validate the will, appoint or confirm an executor, identify assets, pay valid debts and taxes, and distribute remaining property according to the will or state law.
Probate rules vary widely by jurisdiction.
Some assets may avoid probate if they have designated beneficiaries, joint ownership with rights of survivorship, transfer-on-death designations, or are owned by a properly funded trust.
Probate is not always bad. In some situations, it is a necessary and orderly process. But it can take time, involve legal costs, and make certain information public.
A qualified estate planning attorney can explain how probate works where you live and whether any planning tools may be appropriate for your situation.
https://trendminers.online/fire-movement-explained/
Estate Planning and Retirement Accounts
Retirement accounts are often significant assets, especially for people who have spent years contributing to a 401(k), IRA, pension plan, or similar account.
These accounts usually have their own beneficiary designation forms. Your will may not override the beneficiary named on the account.
That is why retirement account beneficiaries should be reviewed regularly.
When selecting beneficiaries, think about:
- Who needs the money
- Whether the person is financially responsible
- Whether they are a minor
- Possible tax consequences
- Whether you need primary and contingent beneficiaries
- Whether a trust may be appropriate
- Whether your choices align with your overall estate plan
Retirement account inheritance rules can be complex. They may involve required distributions, tax consequences, special rules for spouses, and rules for certain beneficiaries.
Speak with an estate planning attorney or tax professional before naming a trust or minor child as a retirement account beneficiary.
For broader retirement planning, revisit Retirement Planning in Your 30s: How Much Should You Save?.
Estate Planning for Homeowners and Rental Property Owners
Real estate can create additional estate planning considerations.
If you own a home, rental property, land, or a share of real estate with another person, you should understand how ownership is titled.
Common ownership structures can include:
- Sole ownership
- Joint tenancy with rights of survivorship
- Tenancy in common
- Community property, in some states
- Ownership through a trust
- Ownership through a business entity
The way property is titled can affect what happens after an owner dies.
For example, jointly owned property may pass automatically to the surviving owner in some cases. Property owned as tenants in common may pass according to a will or state law.
Rental property owners may also need to organize leases, property records, insurance information, vendor contacts, bank accounts, tax records, and management agreements.
If you own investment property, see Rental Income 101: Getting Started With Property Investment for financial planning basics. For legal ownership and inheritance decisions, work with an attorney licensed in your jurisdiction.
Estate Planning for Small Business Owners
Business owners should include their business in their estate plan.
Without a succession plan, a business may face disruption if the owner becomes incapacitated or dies.
Important business planning questions include:
- Who can make decisions if you cannot?
- Who will own the business after your death?
- Should the business be sold, transferred, or closed?
- Where are business records and passwords stored?
- Who can access financial accounts?
- Are there partnership agreements or buy-sell agreements?
- Is there key-person insurance?
- How will employees, customers, and vendors be informed?
If your income comes from digital products, freelancing, consulting, a blog, or another online business, document the systems that keep the business running.
A basic operations guide can help trusted family members or business partners understand what needs immediate attention.
Estate Planning Checklist: How to Get Started
Estate planning may feel overwhelming, but you can begin with simple steps.
Make a List of Your Assets and Debts
Create an inventory of your financial life.
Include:
- Bank accounts
- Retirement accounts
- Investment accounts
- Life insurance
- Property
- Vehicles
- Loans
- Credit cards
- Business interests
- Digital assets
- Valuable personal property
- Income sources
- Recurring bills
Update this list periodically.
Choose Trusted Decision-Makers
Think about who you would trust to serve in important roles.
You may need to choose:
- Executor of your will
- Guardian for minor children
- Financial power of attorney agent
- Healthcare agent
- Trustee, if you create a trust
- Backup representatives
Talk to each person before naming them.
Review Beneficiary Designations
Check retirement accounts, life insurance policies, pensions, and transfer-on-death accounts.
Make sure the listed beneficiaries still match your wishes.
Create or Update a Will
A will can help direct asset distribution, name guardians, and appoint an executor.
Use a qualified attorney when possible, especially if you have children, property, a business, a blended family, or complex assets.
Create Incapacity Documents
A financial power of attorney and healthcare directive can help protect you while you are alive if you become unable to make decisions.
Organize Important Documents
Keep documents in a secure location and tell trusted people how to find them.
Important documents may include:
- Will and trust documents
- Powers of attorney
- Healthcare directives
- Insurance policies
- Property deeds
- Vehicle titles
- Tax records
- Retirement account information
- Bank and investment account details
- Password manager access instructions
- Business records
- Contact information for advisors
Review Your Plan Regularly
Review estate documents after major life changes and at least every few years.
Laws, family relationships, financial accounts, and personal wishes can all change.
Common Estate Planning Mistakes to Avoid
Thinking You Are Too Young or Do Not Have Enough Assets
Estate planning is not only about wealth. It is also about healthcare decisions, guardianship, beneficiaries, and reducing stress for loved ones.
Relying Only on a Will
A will is important, but it may not control beneficiary-designated accounts or jointly owned assets.
Forgetting to Update Beneficiaries
An outdated retirement account or insurance beneficiary can override your current wishes.
Naming Someone Without Talking to Them
Executors, guardians, agents, and trustees should know what you are asking them to do.
Not Planning for Incapacity
Estate planning is not only about death. Financial and healthcare powers of attorney can protect you during illness or injury.
Keeping Information Secret
Your loved ones do not need every financial detail today, but someone trustworthy should know where important documents and account instructions are stored.
Using Generic Documents for Complex Situations
Online templates may be useful for simple needs in some locations, but they may not fit complex family, business, tax, or property circumstances.
Forgetting Digital Assets
Online accounts, cryptocurrency, digital businesses, and passwords need clear planning.
How Estate Planning Supports Long-Term Financial Security
Estate planning works alongside budgeting, investing, insurance, retirement planning, and debt management.
A complete financial plan may include:
- A monthly budget
- Emergency savings
- Appropriate insurance
- Retirement accounts
- Investment diversification
- Debt repayment
- Estate planning documents
- Beneficiary reviews
- Family communication
- Secure document organization
Estate planning can help protect the wealth you build over time.
Whether your assets include a modest savings account, a retirement portfolio, a home, rental property, a business, or passive income sources, a plan can help ensure your hard work benefits the people you choose.
For retirement income planning, read Social Security Benefits: How to Maximize Your Retirement Income.
When to Speak With an Estate Planning Attorney
An estate planning attorney can be especially helpful if you have:
- Minor children
- A blended family
- A child or relative with special needs
- A business
- Significant assets
- Multiple properties
- Real estate in more than one state
- International assets or family members
- Complex tax concerns
- A desire to create a trust
- Concerns about creditor protection
- Family conflict concerns
- A recent marriage, divorce, or death in the family
Even if your situation is simple, a legal professional can help confirm that documents meet your state’s signing, witnessing, notarization, and legal requirements.
Final Thoughts
Estate planning is a practical way to protect your family, your assets, and your wishes.
You do not need to be wealthy or retired to start. A basic plan may include a will, updated beneficiaries, financial and healthcare powers of attorney, an advance directive, and organized financial records.
Start with what you have today. Make a list of your accounts and responsibilities. Choose people you trust. Update your beneficiary designations. Then speak with a qualified estate planning attorney to create documents that reflect your goals and comply with local law.
Preparing now can provide clarity and peace of mind for you and the people you care about.
Legal and Financial Disclaimer: This article is for general educational purposes only and does not provide legal, tax, financial, or estate planning advice. Estate planning laws vary by country, state, and local jurisdiction. Consult a qualified estate planning attorney, tax professional, and financial advisor before creating or changing estate planning documents or beneficiary designations.